The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Loss of rent and tenant default cover can both relate to missed rental income, but they usually respond to different events. This guide explains the common differences, claim triggers, limits and policy conditions Australian landlords should check before relying on either cover.
Loss of rent and tenant default cover are two landlord insurance features that can sound similar because both may relate to interrupted rental income. In practice, they often apply to different causes of missed rent and are usually subject to different limits, exclusions and claim conditions.
For Australian landlords, understanding the distinction can help when comparing landlord insurance policies, reviewing a renewal or deciding whether optional rental income protection is worth considering. This article explains the general difference between loss of rent landlord insurance cover and tenant default cover, what may trigger each one, and what to check in the Product Disclosure Statement before relying on a policy.
Loss of rent cover and tenant default cover: the basic difference
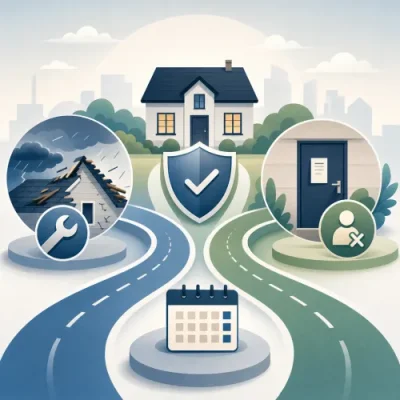
Broadly, loss of rent cover is usually linked to an insured event that prevents the property from being rented or occupied as intended. For example, a storm, fire, flood or serious insured damage event may make a rental property uninhabitable while repairs are completed.
Tenant default cover, sometimes called rent default insurance in Australia, is usually linked to a tenant failing to pay rent, leaving without notice or being lawfully removed under the relevant tenancy process. It is more about the tenant's payment behaviour than the physical condition of the property.
| Feature | Loss of rent cover | Tenant default cover |
|---|
| Main issue addressed | Rental income interruption after an insured event affects the property | Rental income not paid by the tenant in certain circumstances |
| Common trigger | The property cannot be rented or lived in due to insured damage | The tenant defaults on rent, abandons the property or is evicted under policy-recognised conditions |
| Usually connected to | Building or contents damage claim, depending on the policy | Tenancy agreement, rent ledger and legal steps taken by the landlord or property manager |
| Key documents often needed | Evidence of damage, repair timeline, lease details and rental amount | Lease, rent ledger, breach notices, tribunal or court documents where applicable |
| Important limitations | Time limits, insured event requirements, uninhabitable-property rules and exclusions | Waiting periods, excesses, rent arrears limits, tenant screening conditions and legal process requirements |
How loss of rent landlord insurance may work
Loss of rent cover may help with rental income that is interrupted because the rental property cannot be occupied following an insured event. It is commonly discussed alongside building cover because serious property damage can affect whether tenants can safely remain in the home.
For example, if an insured storm damages the roof and the property is not fit for occupation while repairs are being completed, a policy may respond to rental income lost during the insured repair period. Whether it does depends on the policy wording, the insured event, the claim assessment and any applicable limits.
Loss of rent cover may be relevant when:
- the property is damaged by an event covered by the policy;
- the property becomes uninhabitable or cannot be reasonably rented;
- the landlord loses rent during the period needed to repair or reinstate the property;
- the landlord can show the rent that would otherwise have been payable.
Some policies may also use terms such as "rent loss", "rental income cover" or "loss of rental income". These terms are not always interchangeable, so it is important to read the policy definition rather than relying on the heading alone.
How tenant default cover may work
Tenant default cover is generally designed for certain situations where a tenant does not meet their rental payment obligations. It may apply where a tenant stops paying rent, leaves the property owing rent, or is removed after the landlord follows the required legal process.
This cover is often optional or subject to specific conditions. Some insurers may include a form of tenant default cover in a landlord policy, while others may offer it as an add-on or restrict it in certain circumstances. Outcomes depend on the policy terms, the tenancy arrangement and the insurer's assessment of the claim.
Tenant default cover may be relevant when:
- a tenant falls behind on rent beyond any applicable waiting period;
- a tenant abandons the property and rent remains unpaid;
- a landlord or property manager has issued required notices under the relevant state or territory tenancy process;
- a tribunal or court order is needed and obtained where required by the policy;
- rent records and lease documents support the amount claimed.
Tenant default cover should not be assumed to cover every rent shortfall. For example, a policy may not respond if the landlord informally agrees to rent reductions, fails to take required steps, rents to a person who is not on the lease, or cannot provide the documents the insurer asks for.
Why the two covers are often confused
The confusion usually comes from the outcome: the landlord receives less rental income than expected. However, insurers generally look closely at why the rent was lost.
If the rent loss occurred because the property was physically damaged by an insured event and could not be occupied, the claim may sit under loss of rent cover. If the rent loss occurred because the tenant did not pay, abandoned the property or breached the lease in a way recognised by the policy, the claim may sit under tenant default cover.
There can also be overlap. For example, a tenant may damage a property and stop paying rent. The property damage component, tenant damage component and unpaid rent component may each be assessed under different sections of the policy. If tenant damage is a concern, it may help to also review how landlord insurance may treat tenant damage.
Common conditions that may affect a claim
Both forms of cover can be useful, but neither should be treated as automatic rental income protection. Landlord insurance rent loss claims are usually assessed against detailed conditions.
Policy limits and maximum claim periods
Policies commonly place limits on how much rent can be claimed or how long rent loss can be paid. The limit might be expressed as a maximum dollar amount, a number of weeks or months, or a percentage of the insured property value. The exact approach varies by insurer and policy.
Excesses and waiting periods
An excess may apply before the insurer pays a valid claim. Tenant default cover may also include a waiting period or may only respond after rent is overdue for a defined period. These details can materially change the value of the cover.
Lease and tenancy documentation
Insurers often require evidence that the tenancy was properly documented. This may include a written lease, bond records, rent ledger, inspection reports and correspondence with the tenant or property manager.
Legal process requirements
For tenant default claims, insurers may expect landlords to follow the relevant residential tenancy laws in their state or territory. This can include issuing notices correctly, applying to the tribunal where necessary and taking reasonable steps to reduce further loss.
Property condition and maintenance
A claim may be affected if the property was not properly maintained or if damage resulted from gradual deterioration rather than a covered event. Insurance is generally designed for insured risks, not routine wear and tear or avoidable maintenance issues.
Examples of how the distinction may apply
The following examples are general only. Actual outcomes depend on the policy wording, the facts of the claim and the insurer's assessment.
- Storm damage makes the property uninhabitable: loss of rent cover may be the relevant section if the storm is an insured event and the property cannot be occupied during repairs.
- A tenant stops paying rent but remains in the property: tenant default cover may be relevant if the policy includes it and the landlord follows the required steps.
- A tenant leaves owing rent: tenant default cover may respond if abandonment or unpaid rent is covered and the landlord can provide the required evidence.
- A tenant causes malicious damage and rent is interrupted: the claim may involve tenant damage, rent loss and default conditions. Different sub-limits or exclusions may apply.
- The property is vacant between tenants: ordinary vacancy or difficulty finding a new tenant is often not the same as insured loss of rent or tenant default.
What may not be covered
Exclusions vary, but landlords should pay close attention to circumstances where rental income protection may not apply. Common issues can include:
- rent loss caused by general market vacancy or a slow leasing period;
- rent reductions agreed voluntarily without insurer approval;
- informal tenancy arrangements without adequate records;
- failure to issue notices or follow tribunal requirements;
- damage caused by gradual wear and tear, poor maintenance or pre-existing issues;
- short-term rental arrangements not covered by the policy;
- claims arising during extended vacancy beyond the policy's allowed period;
- losses above the policy limit or outside the maximum claim period.
Because exclusions can be technical, it is worth reviewing them before a problem occurs. You can also read more about common exclusions in landlord insurance policies to understand how policy limitations may affect different types of claims.
Questions to ask before choosing rental income protection
When comparing landlord insurance quotes, it can help to ask specific questions rather than simply checking whether "rent loss" is mentioned. Useful questions include:
- Does the policy include loss of rent cover, tenant default cover, or both?
- Is tenant default included automatically or only available as an optional extra?
- What events can trigger loss of rent cover?
- Does the property need to be uninhabitable before loss of rent applies?
- How is the rental amount calculated for a claim?
- What is the maximum amount or period payable?
- Is there an excess, waiting period or minimum arrears period?
- What documents must be kept to support a claim?
- Are periodic leases, share house arrangements or short-term rentals treated differently?
- What steps must be taken before making a tenant default claim?
If you are unsure how a policy would treat your tenancy arrangement, you may wish to seek general guidance from an insurance broker. The broker directory can be a useful starting point for finding help with policy questions, noting that cover availability and terms depend on provider criteria.
How to prepare before a rent loss claim happens
Good records can make a meaningful difference if you need to claim. Landlords and property managers can reduce uncertainty by keeping:
- a signed tenancy agreement and any renewals or variations;
- a complete rent ledger showing payments, arrears and dates;
- entry condition reports, routine inspection reports and photos;
- maintenance records and repair invoices;
- copies of breach notices and tribunal documents where applicable;
- communications with the tenant, property manager and insurer;
- evidence of the usual rent payable for the property.
It is also sensible to contact the insurer promptly if damage, abandonment or significant arrears occur. Delays can affect the claim if they lead to preventable extra loss or if the policy requires prompt notification.
The key takeaway for landlords
Loss of rent cover and tenant default cover both relate to rental income, but they are not the same. Loss of rent cover is usually connected to insured damage that prevents the property from being rented or occupied. Tenant default cover is usually connected to a tenant failing to pay rent, abandoning the property or being removed under recognised tenancy procedures.
Before choosing or renewing landlord insurance, check the policy wording for triggers, limits, waiting periods, exclusions and evidence requirements. The right cover for one rental property may not suit another, and claim outcomes depend on the circumstances, the insurer's criteria and the terms of the policy.
Published: Wednesday, 19th Aug 2026
Author: Paige Estritori


Didn't realise tenant default could hinge so much on notices and rent ledgers, makes me want to check my landlord insurance wording again.